Aswath Damodaran is a professor of finance at NYU Stern whose teaching focuses on valuation and corporate finance. These lessons examine his approaches to valuing businesses, investment decisions, and financial judgment. — NYU Stern — Bio and Mission.
On Intrinsic Valuation
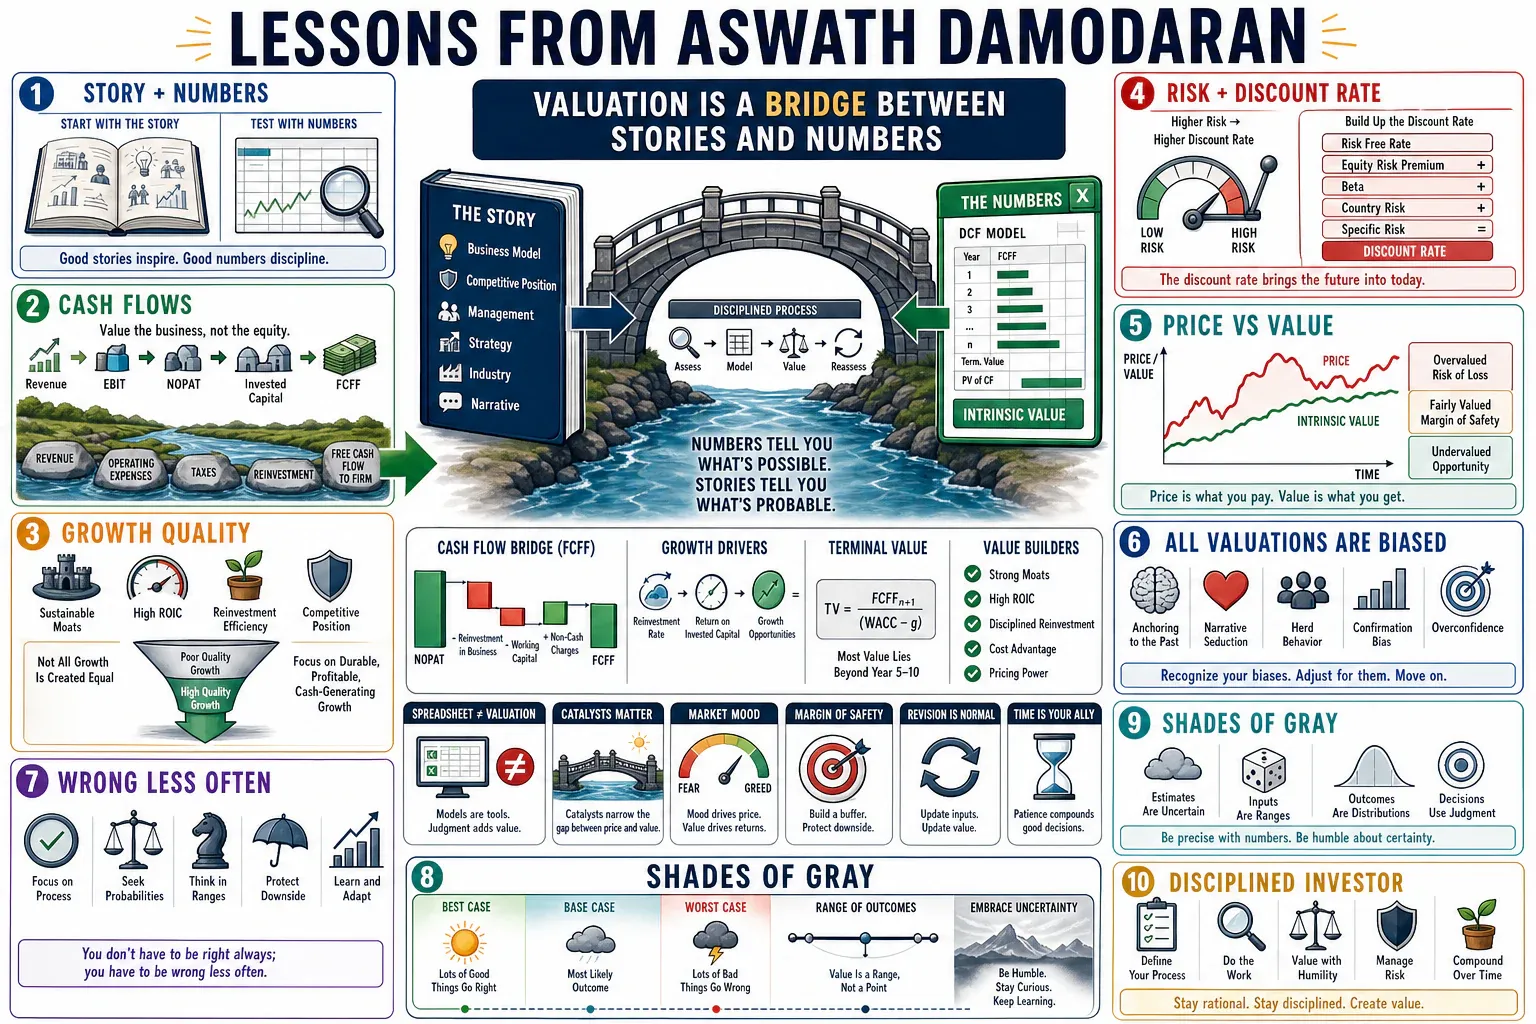
Intrinsic valuation estimates an asset’s value from its expected cash flows and their risk. The result depends on the assumptions used; it is not a perfectly certain discovery of true value. — NYU Stern — Intrinsic versus Relative Value.
- Cash Flows, Growth, and Risk: Estimate intrinsic value from the cash flows an asset can generate, their expected growth, and the uncertainty surrounding them. These are estimates based on assumptions, not a guarantee of an objectively precise value. — NYU Stern — Intrinsic versus Relative Value.
- A Path to Earnings: A young company need not be profitable today to have value, but its valuation needs a credible path to eventual earnings. Forecasting sales alone does not establish that path. — NYU Stern — Young Growth Value Drivers.
- Connect the Story to the Numbers: A business story should explain the assumptions behind a valuation, while the numbers should test whether that story is plausible. Use each to challenge and improve the other. — Narrative and Numbers — Preface.
- Make the Valuation Understandable: Tell the business story behind the spreadsheet. Damodaran argues that a valuation without that explanation is harder to trust and that people remember stories better than spreadsheets. — Narrative and Numbers — Preface.
- Recognize Valuation Bias: Valuations reflect the analyst’s assumptions and preconceptions. Damodaran also warns that who pays for a valuation can influence the direction of its bias; a detailed model does not make the judgment neutral. — NYU Stern — Valuation Introduction.
- A Spreadsheet Is Not an Understanding: Building an Excel model is not the same as understanding a company’s value. The model needs an intelligible business story and assumptions that the analyst can explain. — Morningstar — Damodaran Interview.
- Distinguish Valuation from Pricing: Intrinsic valuation estimates future cash flows and risk. Relative valuation looks at what the market pays for comparable assets, adjusting for meaningful differences; the two approaches need not give the same answer. — NYU Stern — Intrinsic versus Relative Value.
- Judge the Quality of Growth: Assess growth alongside the returns earned on the capital required to produce it. Returns above the cost of capital can create value; expanding the business without that spread does not necessarily do so. — NYU Stern — Financial Measures and Ratios.
- Discount Expected Cash Flows: A discounted cash flow valuation brings expected future cash flows back to the present at a rate that reflects their risk. Cash flow forecasts and the discount rate must be consistent with the claim being valued. — NYU Stern — Intrinsic versus Relative Value.
On Price vs. Value and Market Behavior
Damodaran distinguishes estimating a business’s value from assessing its market price. Fundamentals inform the former, while mood and momentum can influence the latter. — Richer, Wiser, Happier — Meet the Master.
- A Great Business Can Be Overpriced: Separate the quality of a business from the price paid for it. Damodaran’s willingness to sell a business he admires reflects a valuation discipline, not a claim that its stock cannot keep rising. — Richer, Wiser, Happier — Meet the Master.
- Accept Imperfect Estimates: Do not demand certainty from a valuation before using it. Damodaran emphasizes that valuations are imprecise and that uncertainty can otherwise lead to paralysis or blind reliance on other people’s judgments. — NYU Stern — Valuation Introduction.
- Treat Comparables with Care: Relative valuation is more demanding than choosing similar-looking companies. Cash flows, growth and risk affect comparability, and different multiples can produce different answers. A company that looks cheap relative to peers may not be cheap in absolute terms. — NYU Stern — Intrinsic versus Relative Value.
- Price and Value Have Different Drivers: Distinguish changes in market mood and momentum from changes in a business’s cash-generating capacity. Damodaran treats pricing and intrinsic valuation as different tasks, even though both can inform a market decision. — Richer, Wiser, Happier — Meet the Master.
- Use Value as a Price Discipline: For Damodaran, valuation provides a discipline for deciding what to pay and when to sell. That discipline can mean passing on a popular business when its price exceeds his estimate of value. — Richer, Wiser, Happier — Meet the Master.
- Consider How a Price Gap Could Close: An investment based on mispricing also needs an assumption about how and when the market could correct it. A long horizon or a catalyst may matter; estimating a value above today’s price does not guarantee convergence. — NYU Stern — Valuation Introduction.
- Think in Shades of Gray: Damodaran describes his outlook as shades of gray rather than black and white. Treat that as his preference for nuance, not proof that his judgments are free of bias. — Musings on Markets — Investing Politics.
- Doing Nothing Can Be a Decision: During market turmoil, resist acting simply because prices are moving. Damodaran warns that the compulsion to respond can make a difficult situation worse; sometimes doing nothing is the better choice. — Morningstar — Damodaran Interview.
On Corporate Finance and Company Lifecycle
Corporate finance concerns where to invest, how to finance those investments, and when to return cash to owners. The balance between these decisions changes as a company moves through its lifecycle. — NYU Stern — Corporate Finance Principles.
- Growth Needs Investment: Growth from new investments requires reinvestment and depends on the returns those investments earn. Improvements in the efficiency of existing assets can also produce growth, but those gains cannot continue indefinitely. — NYU Stern — Growth Rates.
- Value Future Investments: Growth companies derive much of their value from investments they have yet to make. Valuation therefore needs assumptions about those future opportunities, not just an extrapolation of existing assets. — NYU Stern — Intrinsic versus Relative Value.
- Value Existing Investments: As companies mature, existing investments generally become a larger part of their value. The valuation emphasis shifts toward cash flows from those assets rather than depending primarily on distant growth opportunities. — NYU Stern — Corporate Finance Principles.
- Act Your Corporate Age: Match investment, financing and payout decisions to the company’s stage of life. Damodaran warns that denying maturity or decline can destroy value; a reinvention still needs a credible economic case. — Musings on Markets — Corporate Life Cycle.
- Distinguish Retained Earnings from Value: Paying more dividends leaves less of earnings retained in the business, other things equal. Retained earnings affect book equity, but that accounting change is not itself evidence that shareholder value has increased. — NYU Stern — Financial Measures and Ratios.
- Require a Risk-Appropriate Return: Invest in projects whose expected returns exceed a hurdle rate appropriate to their risk and financing mix. Assess the cash flows and their timing rather than treating growth alone as the objective. — NYU Stern — Corporate Finance Principles.
- Choose Financing to Support Value: Choose the debt and equity mix that best supports firm value, and match financing to the assets being funded. The objective is not simply to maximize borrowing. — NYU Stern — Corporate Finance Principles.
- Return Cash When Opportunities Do Not Qualify: When the business cannot find investments that clear its hurdle rate, return cash to owners. Dividends and buybacks are alternative forms of that decision, informed by cash availability and investment opportunities. — NYU Stern — Corporate Finance Principles.
- Preserve Borrowing Capacity: Borrowing today can limit the ability to fund future opportunities. Give that lost flexibility more weight when future investment needs are substantial or difficult to predict. — NYU Stern — Mature Company Value Drivers.
- Account for Management Equity Grants: Do not treat stock and option compensation as free. Evaluate the cost borne by existing shareholders rather than dismissing it because no cash payment occurs when the award is granted. — Musings on Markets — CEO Compensation.
On Investment Philosophy and Process
An investment philosophy should fit the investor’s temperament and circumstances. Damodaran emphasizes understanding your process without assuming it will control every outcome. — Richer, Wiser, Happier — Meet the Master.
- Keep an Open Investment Mind: Remain open to different types of businesses when the price and evidence warrant it. Damodaran resists permanent exclusions such as never buying a particular category; this is a personal investing approach, not a promise of superior returns. — Excess Returns — Damodaran Interview.
- Admit and Learn from Mistakes: Admitting that an investment judgment was wrong makes it possible to correct it. Damodaran urges investors to keep a feedback loop open rather than defend a decision merely because it was their own. — Excess Returns — Damodaran Interview.
- Do Not Confuse Complexity with Insight: More inputs and a more quantitative model do not automatically produce a better valuation. Favor assumptions you understand over complexity that obscures the judgment being made. — NYU Stern — Valuation Introduction.
- Seek Contrary Evidence: Do not let attachment to a business story override discordant facts. Damodaran recommends spending less time exclusively with people who think like you, so that your assumptions face a genuine challenge. — Morningstar — Damodaran Interview.
- Separate Process from Outcomes: A sound investment process does not ensure a favorable outcome. Damodaran stresses accepting what is outside your control and learning from what happens rather than judging every decision solely by its reward. — Richer, Wiser, Happier — Meet the Master.
- Leave Room to Daydream: Make time for unstructured thinking before immediately searching for someone else’s answer. Damodaran values daydreaming as a way to consider what he might do differently or learn next. — Richer, Wiser, Happier — Meet the Master.
- Connect Ideas Across Disciplines: A generalist can connect questions across areas of finance even without matching each specialist’s depth. Damodaran describes that breadth as his advantage, rather than claiming that specialization is inherently inferior. — Richer, Wiser, Happier — Meet the Master.
- Understand Activist Value Investing: Activist value investing targets poorly managed companies and seeks to change how they are run. Damodaran presents it as a distinct investment approach, not as a strategy suited to every investor. — NYU Stern — Investment Philosophies.
- Know What You Bring to the Table: Ask what insight or capability you contribute beyond a readily reproducible screen. Damodaran warns against expecting an investing advantage from a method that others can copy easily. — Excess Returns — Damodaran Interview.
- Be Honest About Why You Invest: Damodaran says he enjoys making his own investment decisions and is comfortable with the possibility of not beating the market. Distinguish that personal motivation from evidence that active investing will outperform. — Excess Returns — Damodaran Interview.
Additional Learnings and Insights
- On ESG: Damodaran argues that if ESG makes a company safer, a lower required return would follow—not automatically excess returns for investors. This is his conditional reasoning, not evidence that every ESG strategy lowers risk. — Richer, Wiser, Happier — Meet the Master.
- On Risk: Consider both the downside and the opportunity in risk. The aim is to incorporate risk into investment choices, not assume that avoiding every uncertain outcome is the best policy. — NYU Stern — Investment Philosophies.
- On Macroeconomic Forecasting: Damodaran is skeptical of macroeconomic forecasting and the sense of control it can provide. He distinguishes those broad forecasts from the company-level judgments on which he prefers to focus. — Richer, Wiser, Happier — Meet the Master.
- On Humility: Leave room for being wrong about an investment and for luck in the result. Damodaran cautions against treating success as proof of skill or conviction as proof that an estimate is correct. — Richer, Wiser, Happier — Meet the Master.
- On Dealing with Market Noise: Do not waste energy resenting the market or investors using a different approach. Damodaran argues that such anger can damage your own process without changing how the market behaves. — Richer, Wiser, Happier — Meet the Master.
- On Valuing Young Companies: For a young company, estimate the market it can reach, its potential share, the path to profitable margins, and the investment needed to get there. Include the possibility that the company will not survive; growth forecasts alone are insufficient. — NYU Stern — Young Growth Value Drivers.
- On Valuing Mature Companies: Look for improvements in existing operations, financing, and management of non-operating assets. Damodaran’s framework asks how those changes could affect cash flows and value instead of relying on a return to youthful growth. — NYU Stern — Mature Company Value Drivers.
- On Teaching: Damodaran describes himself as a teacher first and shares substantial teaching materials openly. His stated aim is to help people learn finance, not just those enrolled in his classes. — NYU Stern — Bio and Mission.
Sources:
- Aswath Damodaran — Bio and Mission Statement
- The Little Book of Valuation — Intrinsic versus Relative Value
- RWH005: Meet the Master w/ Aswath Damodaran
- Corporate Finance: What Is It? — Applied Corporate Finance
- The Little Book of Valuation — Young Growth Companies: Value Drivers
- Narrative and Numbers — Preface and Chapter Outline
- Valuation Introduction — Spring 2025
- Aswath Damodaran’s Thoughts on Volatility, Valuation … and Even ESG
- Financial Measures and Ratios — Aswath Damodaran
- Investing Politics: Globalization Backlash and Government Disruption!
- The Little Book of Valuation — Growth Rates
- The Compressed Tech Life Cycle: The Managerial Challenge
- The Little Book of Valuation — Mature Companies: Value Drivers
- Is Your CEO Worth His (Her) Pay? The Pricing and Valuing of Top Managers!
- The Value Investing Delusion | Aswath Damodaran on Why Value Investors Missed the Mag Seven
- Investment Philosophies — Aswath Damodaran