Edward Chancellor is a financial historian and journalist whose books examine speculation, interest rates and the capital cycle. He edited and introduced Capital Returns, a collection of Marathon Asset Management reports on industry investment cycles. — Edward Chancellor — Capital Returns.
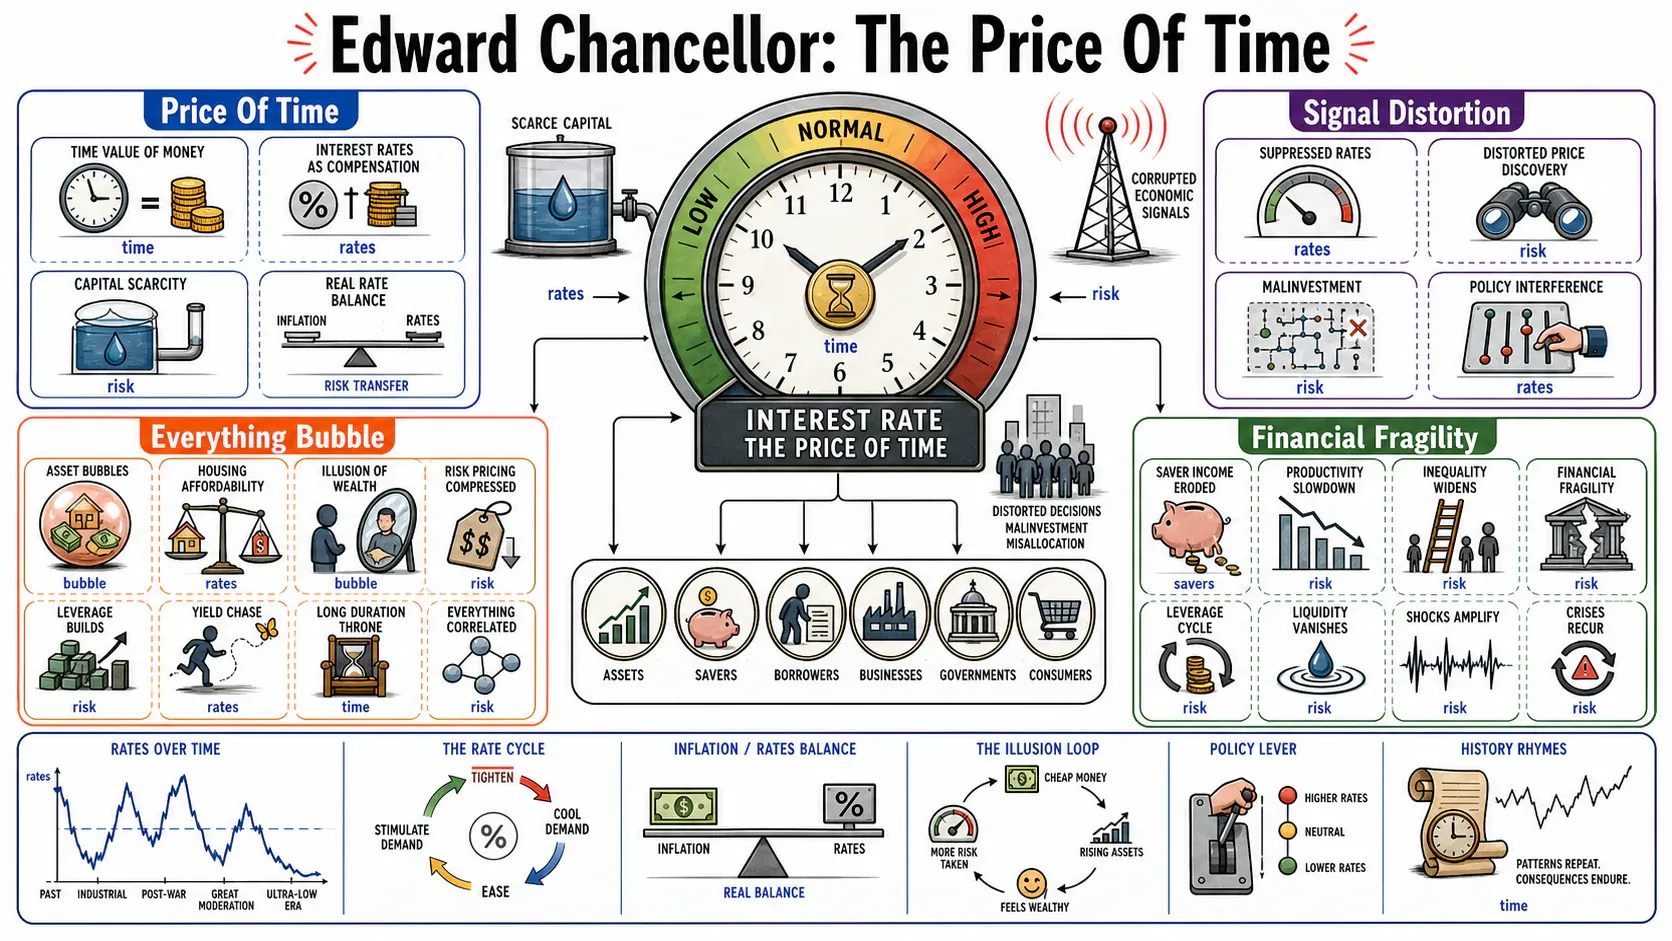
On Interest Rates: The Price of Time
Chancellor treats interest as the price of time and argues that suppressing that price can distort investment, asset valuation and risk-taking. These are his historical and economic arguments, not guaranteed effects in every setting. — The Price of Time — Publisher Excerpt.
- On the Price of Time: Chancellor describes the broadest account of interest as the time value of money: a price attached to moving resources across time, while acknowledging that other interest theories capture parts of the picture. — The Price of Time — Publisher Excerpt.
- On Why Interest Exists: Chancellor gives several reasons for interest: resources are scarce, loans can be productive and risky, production takes time, and people tend to prefer present consumption. — The Price of Time — Publisher Excerpt.
- On Interest and Capitalism: Chancellor argues that interest helps coordinate saving and investment across time, price future income streams and set investment hurdle rates; he sees these functions as especially important in a capitalist economy. — The Great Simplification — Chancellor Interview.
- On Ultra-Low Rates: Chancellor's thesis is that ultra-low interest rates contributed to weak productivity, costly housing, inequality, reduced competition and financial fragility; he presents these as related mechanisms, not a single proven cause of each outcome. — The Price of Time — Publisher Excerpt.
- On the Rate as a Signal: Chancellor argues that market-determined interest rates help guide capital allocation and valuation. He also cautions that the natural rate cannot be directly observed, so the right level is not mechanically knowable. — The Price of Time — Publisher Excerpt.
- On the Everything Bubble: Chancellor argues that very low discount rates inflated valuations across many assets, contributing to what he calls an 'everything bubble.' He treats any later reversal as conditional rather than inevitable. — The Great Simplification — Chancellor Interview.
- On Savers and Cheap Credit: Chancellor contrasts depositors receiving negative real returns with wealthier borrowers able to obtain cheap credit; the effect depends on each household's mix of deposits, housing and equities. — Top Traders Unplugged — Chancellor Interview.
- On Illusory Wealth: Chancellor argues that falling interest rates can lift asset valuations even as underlying saving weakens, creating wealth that is vulnerable to a change in discount rates. — The Great Simplification — Chancellor Interview.
- On Historical Rate Patterns: Chancellor observes U-shaped interest-rate patterns in several ancient civilizations, with low rates sometimes preceding upheaval. He does not present this as a universal forecasting rule. — The Price of Time — Publisher Excerpt.
- On Early Productive Loans: Chancellor traces ancient interest-bearing loans in grain and other productive resources, while acknowledging that the precise origin of interest is not settled by one type of contract. — The Price of Time — Publisher Excerpt.
On Financial Speculation and Bubbles
Chancellor studies recurring speculative manias while emphasizing that real investors exhibit crowd instincts, greed, fear and other behavior missing from a purely efficient-market account. — PBS FRONTLINE — Devil Take the Hindmost Excerpt.
- On Credit and Speculation: Chancellor's study of manias led him to examine how credit and monetary policy can amplify speculative episodes, including the dot-com and subsequent credit booms. — Top Traders Unplugged — Chancellor Interview.
- On Recurring Manias: Chancellor compares apparently novel booms with earlier manias, while examining the specific credit and institutional conditions of each episode. — Top Traders Unplugged — Chancellor Interview.
- On the Pandemic-Era Mania: Chancellor agreed with Charlie Munger's assessment that the 2020–21 markets were unusually speculative, adding that he could think of few aggregate markets as extreme in his historical reading. — The Great Simplification — Chancellor Interview.
- On Crowd Psychology: Chancellor argues that greed, fear, crowd instincts and trend-following can shape speculative episodes in ways a purely efficient-market account misses. — PBS FRONTLINE — Devil Take the Hindmost Excerpt.
- On a Bubble's Aftermath: Chancellor notes that overbuilt infrastructure may later benefit consumers, but investors can still suffer heavy losses and the excess capacity can depress returns; a useful legacy does not prove the original investment was efficient. — Top Traders Unplugged — Chancellor Interview.
- On Leverage and Fragility: Chancellor argues that cheap borrowing can encourage leverage and duration risk, making a financial system more sensitive when interest rates rise. — The Great Simplification — Chancellor Interview.
- On Boom and Bust: Chancellor regards periods of boom and bust as a recurring feature of market-based systems; that is his assessment, not a precise forecast of the next cycle. — unSILOed — Chancellor Interview.
On the Capital Cycle and Investment Strategy
Chancellor edited and introduced Capital Returns, a collection of Marathon Asset Management reports. In his own account, the capital-cycle lens looks at industry supply and investment flows rather than relying on demand forecasts alone. — Edward Chancellor — Capital Returns.
- On the Capital Cycle: Chancellor advises examining where capital is entering or leaving an industry: rising capacity can erode returns even in a fast-growing market, while restrained supply can improve the outlook for mature businesses. — MoneyWeek — Capital-Cycle Interview.
- On Capital Allocation: Chancellor argues that the scale and timing of investment can materially affect later shareholder returns; valuation alone misses how much industry capacity is being built. — MoneyWeek — Capital-Cycle Interview.
- On Supply and Competition: Chancellor emphasizes that demand narratives are hard to forecast, while capacity under construction is more observable; added supply can intensify competition and pressure industry profitability. — MoneyWeek — Capital-Cycle Interview.
- On Cash Conversion: Chancellor suggests checking whether reported profits turn into cash alongside industry investment: strong accounting earnings can conceal a vulnerable phase of the capital cycle. — MoneyWeek — Capital-Cycle Interview.
- On Capacity as a Warning: A rapid rise in industry assets or production capacity can be a warning even when recent profits and share valuations still look attractive; Chancellor uses US homebuilders as a case. — MoneyWeek — Capital-Cycle Interview.
- On Consolidation After a Bust: Chancellor contrasts consolidated UK homebuilders with overbuilt US peers after the housing bust; reduced capacity can change future competition, though consolidation alone does not guarantee returns. — MoneyWeek — Capital-Cycle Interview.
- On Intelligent Contrarianism: Chancellor says contrarian instinct is not enough: investors should consider how far an industry has moved through its capital cycle before buying a stock that appears cheap. — MoneyWeek — Capital-Cycle Interview.
- On Measuring Investment: Chancellor suggests tracking asset growth, new debt and equity issuance, capital spending relative to depreciation, and cash conversion to gauge where an industry stands in its cycle. — MoneyWeek — Capital-Cycle Interview.
- On Overbuilding Before Busts: Chancellor points to fiber-optic and housing overbuilding as cases where a surge in capital spending preceded severe losses; he uses supply buildout as a risk signal, not a precise crash clock. — MoneyWeek — Capital-Cycle Interview.
Learnings on the Broader Economy and Society
Chancellor extends his interest-rate analysis from financial markets to productivity, debt, pensions, inequality and the resilience of the wider economy. These are claims he argues in his own written evidence. — UK Parliament — Chancellor Written Evidence.
- On Zombie Firms: Chancellor argues that zero rates can act as loan forbearance, allowing indebted low-return firms to remain in business rather than releasing capital and capacity for other uses. — Top Traders Unplugged — Chancellor Interview.
- On Productivity and Entry: In Chancellor's account, sectors crowded with zombie firms can have fewer entrants, less investment and weaker productivity because capital remains tied to low-return incumbents. — Top Traders Unplugged — Chancellor Interview.
- On Speculative Ventures: Chancellor argues that very cheap capital can fund ventures whose appeal depends on distant profits or rising valuations, diverting resources from investments with clearer productive returns. — Top Traders Unplugged — Chancellor Interview.
- On Pension Risk: Chancellor argues that ultra-low rates made retirement security harder to obtain and contributed to pension-system vulnerability; his written evidence cites UK pension funds' exposure when gilt yields rose. — UK Parliament — Chancellor Written Evidence.
- On Distributional Effects: Chancellor contends that low rates can widen wealth gaps by lifting asset values for owners while weak productivity restrains incomes for others; he particularly notes older-versus-younger differences. — UK Parliament — Chancellor Written Evidence.
- On Indirect Costs: Chancellor argues that cheap financing can lengthen global supply chains, making them potentially more vulnerable when funding costs rise or other disruptions strike. — Top Traders Unplugged — Chancellor Interview.
- On Political Discontent: Chancellor sees a possible link between low rates, globalized supply chains, weak wage growth and political discontent, while saying the causal chain is not provable from his account. — Top Traders Unplugged — Chancellor Interview.
- On Financial Fragility: Chancellor argues that prolonged cheap money encouraged more debt and risk-taking, leaving parts of the system sensitive to higher interest rates; this is a risk diagnosis, not a dated crisis forecast. — UK Parliament — Chancellor Written Evidence.
- On Monetary Policy and Risk: Chancellor argues that a narrow inflation target can miss asset and credit imbalances; in his view, suppressing interest rates can encourage risk-taking even when consumer prices appear stable. — UK Parliament — Chancellor Written Evidence.
- On Stable Prices and Credit Booms: Chancellor points to the 1920s as a case in which quiet consumer-price inflation coexisted with a credit boom; stable prices alone did not rule out financial imbalance. — The Price of Time — Publisher Excerpt.
Additional Insights and Reflections
- On Financial Writing: After decades writing about finance, Chancellor says established thinking can be resistant to new ideas; he prefers to describe problems and possible solutions rather than claim to invent them. — unSILOed — Chancellor Interview.
- On QE and Public Finances: Chancellor argues that quantitative easing effectively exchanged longer-term government debt for short-term central-bank reserves, increasing the UK public finances' exposure to rises in Bank rate. — UK Parliament — Chancellor Written Evidence.
- On Historical Economic Thought: Chancellor argues that earlier economic thinkers can illuminate credit and interest-rate problems that are easy to neglect when analysis is confined to formal models. — Top Traders Unplugged — Chancellor Interview.
- On Forecasting Limits: Chancellor uses history to identify possible vulnerabilities, but his discussion of successive credit booms does not offer a reliable clock for the next crisis or a guarantee that it will take the same form. — Top Traders Unplugged — Chancellor Interview.
- On the Aftermath of Easy Money: Chancellor warns that the consequences of ultra-low rates can emerge when rates rise: his written evidence points to losses on bonds, pension strategies and bank holdings. These examples support a vulnerability, not a certain future catastrophe. — UK Parliament — Chancellor Written Evidence.
Sources
- Edward Chancellor — Capital Returns
- The Price of Time: The Real Story of Interest — Official Publisher Excerpt
- Top Traders Unplugged — The History of Interest & the Next Devastating Crisis, Edward Chancellor Interview
- unSILOed Episode 324 — Edward Chancellor on the History of Interest Rates
- UK Parliament — Edward Chancellor Written Evidence on Bank of England Independence
- The Great Simplification — Edward Chancellor Interview Transcript
- PBS FRONTLINE — Devil Take the Hindmost Excerpt by Edward Chancellor
- Edward Chancellor: 'intelligent contrarians' should follow the capital cycle — MoneyWeek