François Rochon founded Giverny Capital after managing a family portfolio and studying investors including Warren Buffett and Philip Fisher. His letters explain a long-term approach to owning strong businesses at prices he considers reasonable, while acknowledging that results and valuations remain uncertain. — Giverny Capital — 2020 Annual Letter.
On Investment Philosophy
- Oscar Wilde as a Quality Motif: Rochon placed Oscar Wilde’s “I only like the best” line above the “Our businesses” section of his 2001 letter. The quotation is Wilde’s; Rochon used it to introduce his preference for outstanding companies. — Giverny Capital — 2001 Annual Letter.
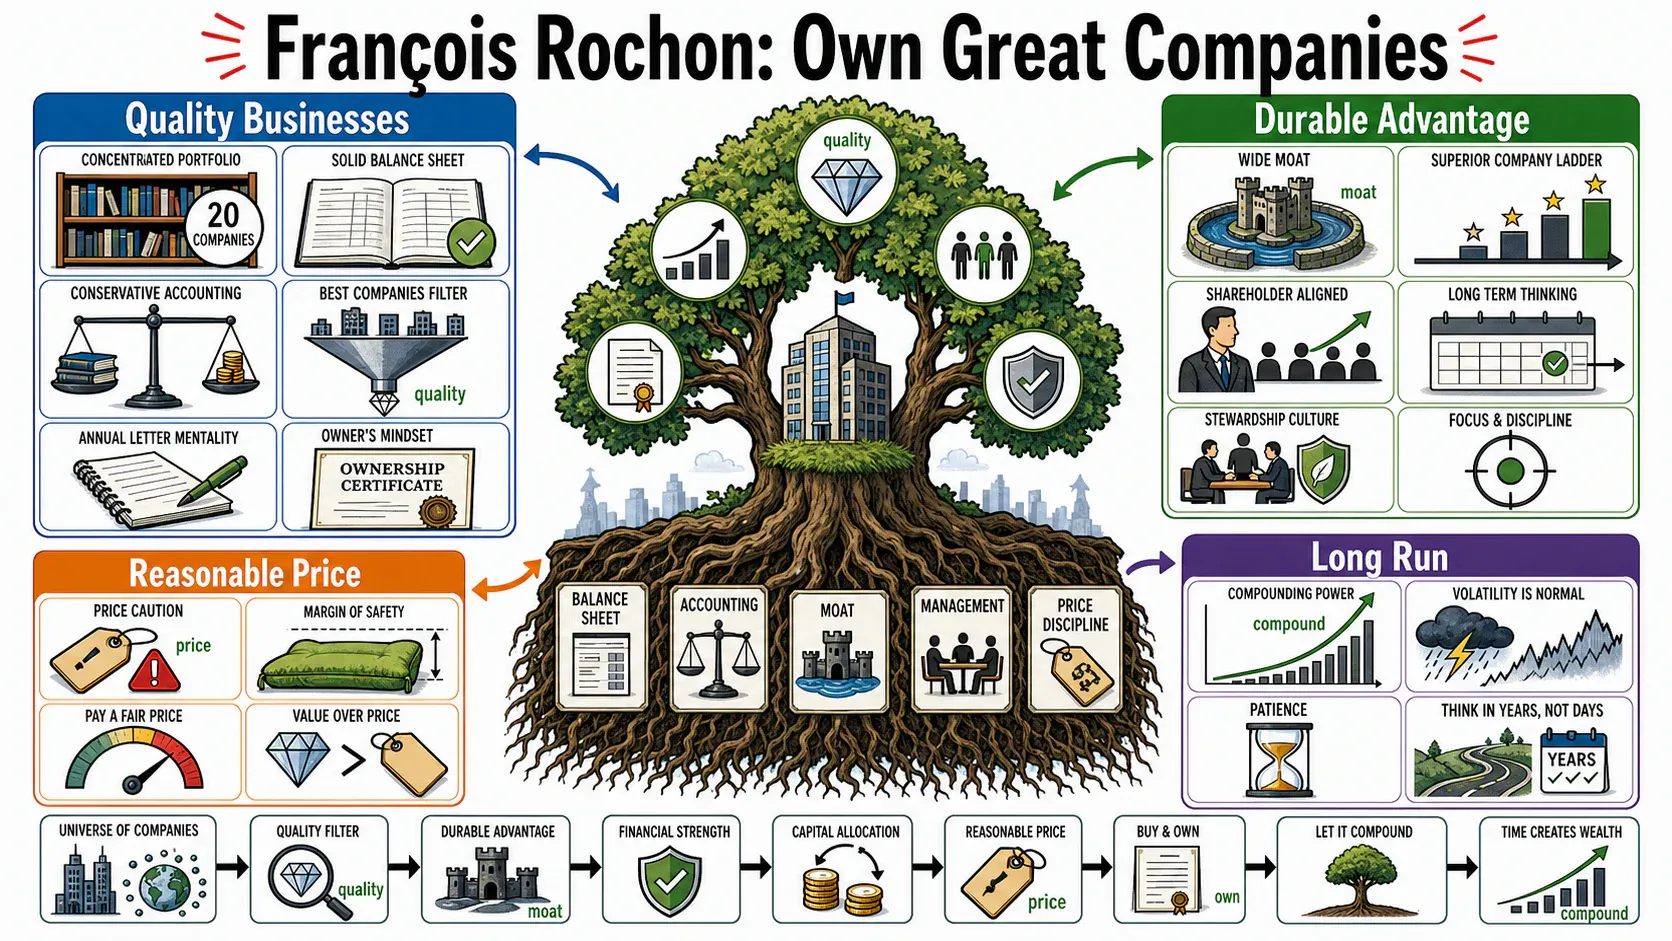
- Quality at a Reasonable Price: In his 2020 letter, Rochon described holding roughly twenty companies with sound balance sheets, conservative accounting, durable advantages and shareholder-minded managers, while staying careful about purchase price. — Giverny Capital — 2020 Annual Letter.
- Own Businesses, Not Tickers: Rochon describes investing as owning parts of businesses and judging them by their earnings and long-term prospects rather than daily quotations. — Giverny Capital — 2020 Annual Letter.
- Seek Better-Than-Average Businesses: In the 2022 letter, Rochon argued that outperforming an average index requires owning businesses with above-average qualities and some ability to shape their own prospects. — Giverny Capital — 2022 Annual Letter.
- Seek Faster Intrinsic-Value Growth: In a 2015 interview, Rochon said his stock-selection aim was to find businesses whose earnings and intrinsic value could grow faster than the average company. It was an investment objective, not a forecast that any holding would achieve it. — Value Investor Insight — François Rochon Interview.
- Value Means Paying Below Worth: Rochon calls himself a value investor: he tries to purchase a business for less than he estimates it is worth. — Compounding Quality — François Rochon Interview.
- Value Includes Quality and Growth: He rejects reducing value investing to low price-to-earnings or book-value ratios; business quality, durable advantages and future growth also matter to his valuation. — Compounding Quality — François Rochon Interview.
- Margin of Safety Beyond Price: Rochon extends margin of safety beyond the purchase price to the quality of the business, its managers and its balance sheet. — The Investor’s Podcast — The Best of the Best.
- Accept Delayed Gratification: He says long-term investing can require short-term discomfort before a company’s results are reflected in its share price. — Compounding Quality — François Rochon Interview.
- Practice Humility, Rationality and Patience: Rochon names humility, rationality and patience as advantages for an investor: accept limits of prediction, learn from errors and keep attention on businesses. — Talks at Google — The Art of Investing.
On Market Perspective and Long-Term Thinking
- Do Not Extrapolate a Market Fashion: Rochon warned in his 2020 letter that investors can project a fashionable sector’s growth too far into the future and pay a price that assumes too much. — Giverny Capital — 2020 Annual Letter.
- Do Not Predict Near-Term Markets: Rochon argues that the timing of market rises and falls is not reliably predictable and instead focuses on selecting businesses. — Giverny Capital — 2020 Annual Letter.
- Let Business Value Guide a Long Horizon: Rochon’s letters argue that, over long periods, stock prices tend to reflect the intrinsic value created by the underlying businesses, even though short-term prices can diverge. — Giverny Capital — 2020 Annual Letter.
- Remember What a Share Owns: When crises shift attention to market prices, Rochon returns to the fact that a share is an ownership interest in a business whose economics must be evaluated. — Giverny Capital — 2020 Annual Letter.
- Use Volatility Selectively: Rather than treating every price decline as damage, Rochon regards volatility as a chance to buy a business below his estimate of intrinsic value—if its fundamentals remain sound. — Giverny Capital — 2020 Annual Letter.
- Think in Decades, Not Quarters: In a direct interview, Rochon urges a decades-long perspective when evaluating businesses and investment behavior. — Compounding Quality — François Rochon Interview.
- Prepare for Bear Markets With Resilient Businesses: Rochon says he looks for profitable companies with healthy balance sheets and limited sensitivity to economic conditions as a way to withstand bear markets. — Compounding Quality — François Rochon Interview.
On Company Selection and Analysis
- Study a Business’s History: Rochon starts with businesses that have demonstrated profitability and durable advantages, using their record as an initial test of quality. — Value Investor Insight — François Rochon Interview.
- Test Resilience Through Downturns: He examines whether a business model and balance sheet can withstand adverse conditions; his 2020 letter discussed how portfolio companies handled that year’s shock. — Giverny Capital — 2020 Annual Letter.
- Do Not Let Past Numbers Replace Judgment: Rochon says historical figures matter, but extrapolating them mechanically can miss changes in human behavior, business quality and future prospects. — Talks at Google — The Art of Investing.
- Inspect the Business Model: His selection process asks whether a company leads its market, has a durable advantage and has a business model he can understand. — Talks at Google — The Art of Investing.
- Inspect the Financial Structure: Rochon favors profitability, conservative debt and a sound balance sheet alongside the company’s business model. — Value Investor Insight — François Rochon Interview.
- Assess Management’s Capital Allocation: He looks for competent, shareholder-focused managers who allocate capital well and think beyond the next quarter. — Talks at Google — The Art of Investing.
- Estimate Future Growth Conservatively: Rochon considers whether a company can grow earnings and intrinsic value over several years; he treats the forecast as an approximate judgment, not a precise calculation. — Value Investor Insight — François Rochon Interview.
- Compare Price With Estimated Value: After judging business quality, Rochon estimates future earnings and an appropriate valuation to decide whether today’s stock price offers a margin of safety. — Compounding Quality — François Rochon Interview.
On Management and Leadership
- Require Capable Stewards: Rochon emphasizes management competence and long-term stewardship, including decisions about reinvestment and acquisitions. — Value Investor Insight — François Rochon Interview.
- Prefer Management With Ownership: In his 2017 talk, Rochon said he favors senior managers with meaningful share ownership so their incentives resemble those of shareholders. — Talks at Google — The Art of Investing.
- Align Giverny and Its Clients: Rochon wrote that he manages client portfolios in the same manner as his own family portfolio and wants clients and managers “in the same boat.” — Giverny Capital — 2020 Annual Letter.
On the Art of Investing
- Learn an Investing Craft: Rochon likens investing to an art: study strong predecessors, practice, develop independent judgment and keep improving rather than simply copying a formula. — Talks at Google — The Art of Investing.
- Recognize an Exceptional Business: In 2017 Rochon called Constellation Software a “masterpiece” and praised its distinctive culture and long-term leadership. This was his assessment at the time, not a current stock recommendation. — Talks at Google — The Art of Investing.
- Look for Quality Beyond the Spreadsheet: For Rochon, an unusually strong business can have an aesthetic quality: rare economics, superior margins and an advantage that numbers alone do not fully explain. — Talks at Google — The Art of Investing.
- Wait for a Suitable Pitch: Rochon uses Warren Buffett’s “no called strike” analogy to explain that investors can wait for a business and valuation within their circle of competence. — Talks at Google — The Art of Investing.
On Portfolio Management and Selling
- Balance Diversification With Concentration: Rochon explained that roughly 20 to 25 positions feels to him diverse enough to limit single-name damage yet concentrated enough for stock selection to matter. — The Investor’s Podcast — The Best of the Best.
- Sell When the Investment Case Breaks: Rochon says a mistake, deteriorating fundamentals or a changed business can justify selling; patience must not become stubbornness. — Talks at Google — The Art of Investing.
- Avoid Hard-to-Underwrite Sectors: In a 2025 interview, Rochon said his firm generally avoids commodities, utilities and some healthcare businesses where durable advantages or regulatory outcomes are hard to assess. — The Investor’s Podcast — The Art of Long-Term Investing.
On Personal Qualities of an Investor
- Humility Means Knowing Predictive Limits: Rochon connects investment humility with not pretending to forecast macroeconomic events and with recognizing the boundaries of his circle of competence. — Talks at Google — The Art of Investing.
- The “Missing Gene” Is a Metaphor: Rochon uses a “missing tribal gene” metaphor for independent-minded investors who can dissent from a crowd. It is figurative, not a claim about genetics. — The Investor’s Podcast — The Best of the Best.
- Watch Earnings While Waiting: Using CarMax as an example, Rochon said an investor waiting through stock-price swings should examine the company’s earnings and business progress, not just the quotation. — Talks at Google — The Art of Investing.
- Start With What to Avoid: Rochon says he begins by excluding businesses whose competitive advantages he finds difficult to establish, while allowing that there can be exceptions. — Best Anchor Stocks — François Rochon Conversation.
Sources
- Giverny Capital — 2001 Annual Letter
- Giverny Capital — 2020 Annual Letter
- Giverny Capital — 2022 Annual Letter
- Giverny Capital — 2024 Annual Letter
- Talks at Google — The Art of Investing
- The Investor’s Podcast — The Best of the Best
- Compounding Quality — François Rochon Interview
- Best Anchor Stocks — François Rochon Conversation
- Value Investor Insight — François Rochon Interview
- The Investor’s Podcast — The Art of Long-Term Investing