Harvey Sawikin co-founded Firebird in 1994 and has invested across Eastern Europe. A former M&A lawyer, he writes about investing and art on The Falling Knife. This profile examines his direct accounts of due diligence, frontier markets, portfolio judgment and career choices. — Value Investing and Art Collections.
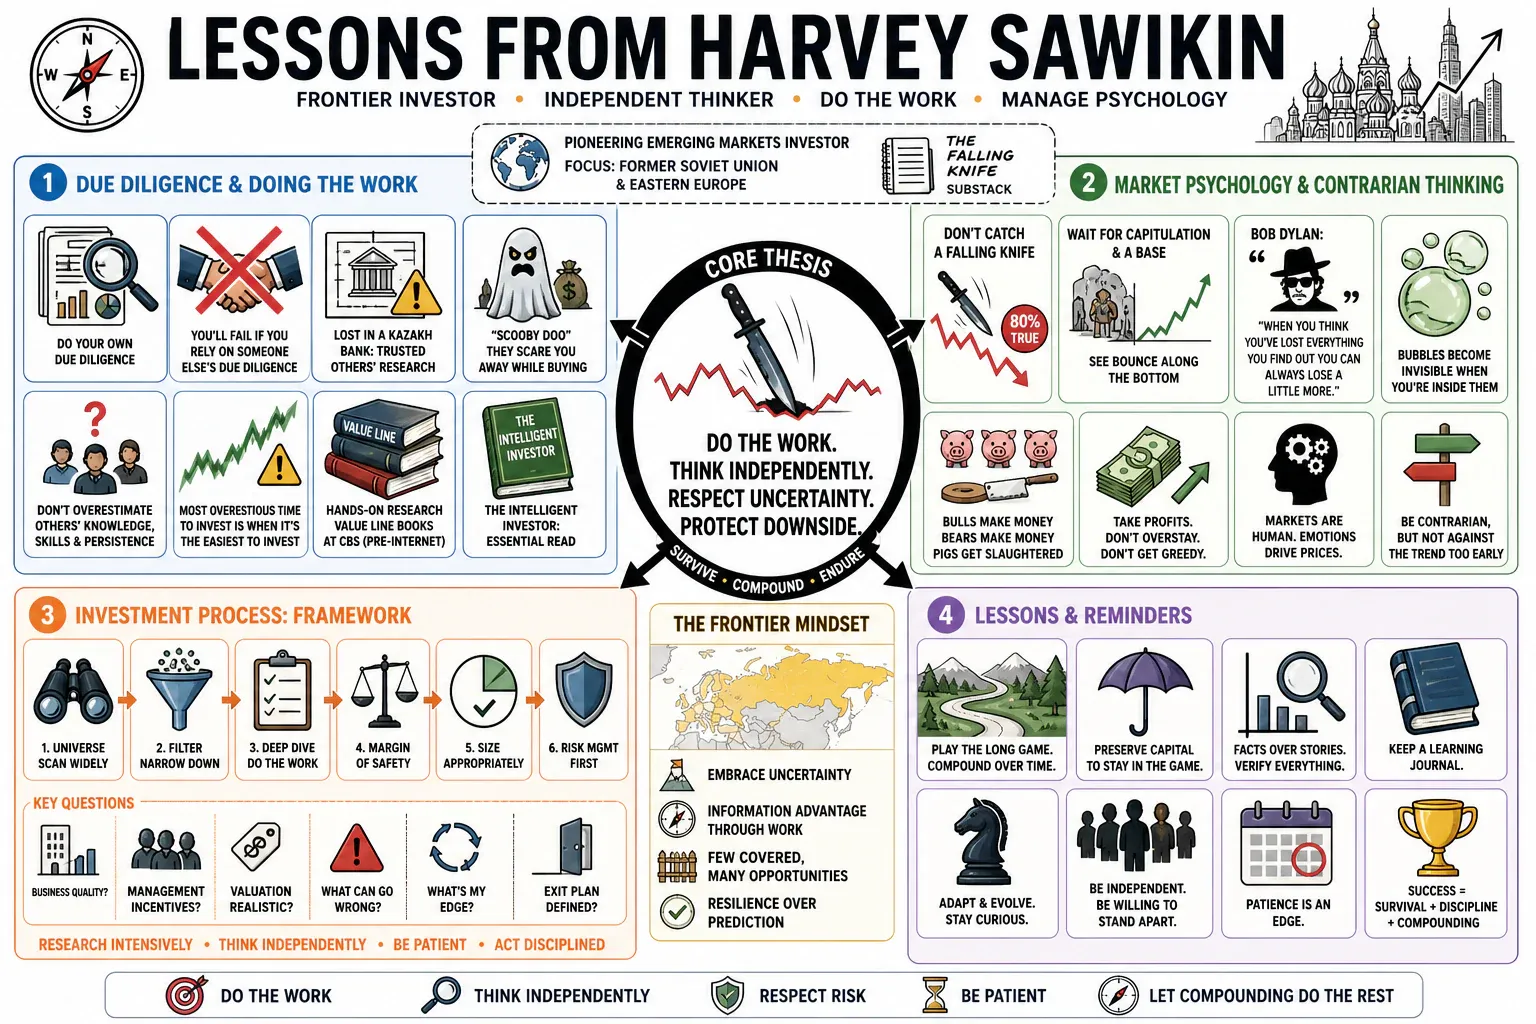
On Due Diligence and Doing the Work
- Do your own diligence: Sawikin says losses in a Kazakh bank and a Ukrainian vodka company taught him not to rely on another fund's investigation in place of his own. — My Worst Investment Ever Interview.
- Notice discouraging management: Sawikin recalled that Uralkali's management discouraged Firebird from buying shares while buying for itself; his team called that scare-off tactic the “Scooby Doo.” — Graham & Doddsville Interview.
- Beware easy money in a bubble: Reflecting on the 2006–07 emerging-markets bubble, Sawikin says rapid inflows and fear of missing out led him to lower investment standards and enter private deals that became hard to exit. — My Worst Investment Ever Interview.
- A book opened the door: After Sawikin left his law firm, a partner gave him Benjamin Graham's The Intelligent Investor and urged him to read it as a serious prospective investor. — Graham & Doddsville Interview.
- Do the pre-internet research: In 1992, Sawikin searched Value Line volumes at Columbia Business School for stock ideas before online research was available. — Graham & Doddsville Interview.
On Market Psychology and Contrarian Thinking
- A falling knife may fall further: Sawikin rates the warning against catching a falling knife mostly sound: a plunging stock can continue falling far beyond a buyer's apparent bargain price. — Investing Truisms.
- Wait for a base: For a collapsing stock, Sawikin generally prefers to wait for selling to exhaust itself and a bottom to form before buying, while allowing for exceptions in illiquid shares. — Investing Truisms.
- Bubbles obscure their own risks: Sawikin says the 2006–07 bubble made heavy inflows and soaring fund returns feel normal even as his team was taking more risk. — My Worst Investment Ever Interview.
- Do not trim every winner: Sawikin challenges the maxim that investors must always take profits: for many long-term investors, repeatedly selling their strongest companies can be a mistake. — Investing Truisms.
- Pessimism is not automatically profitable: When assessing the bulls-and-bears adage, Sawikin says his experience makes him skeptical that bearish positioning reliably creates wealth. — Investing Truisms.
- Question the anti-pig maxim: Sawikin recalls a law-firm partner joking that his best clients were professional “pigs,” an anecdote he uses to challenge automatic profit-taking rather than to endorse recklessness. — Investing Truisms.
- Reverse a mistaken trade: Sawikin says an investment made on intuition should be reconsidered promptly when the underlying judgment changes; he rates the advice to reverse a mistake as mostly sound. — Investing Truisms.
- Look for perception gaps: Sawikin argues that frontier markets can have larger gaps between outside perceptions and local realities than better-covered emerging markets, creating both opportunity and analytical risk. — Graham & Doddsville Interview.
- Avoid fighting the last war: Sawikin warns that investors often focus on the macro shock that hurt them most recently and can miss a shift back toward company-specific opportunities. — Graham & Doddsville Interview.
On Emerging and Frontier Markets
- Test whether outsiders can invest: Before entering a market, Sawikin asks whether foreign investors can participate, whether there are worthwhile listed companies, and how political risks affect the opportunity. — Invest Like the Best Podcast.
- Watch the dollar in emerging markets: Sawikin sees the U.S. dollar as an important inverse correlate of emerging-market performance, especially alongside global growth and inflation; this is his investment view, not a universal rule. — Trump Smash Dollar.
- Seek political stabilization: Sawikin's early-market screen begins with political change that has made a country more stable, rather than growth statistics alone. — Graham & Doddsville Interview.
- Seek macroeconomic stabilization: Sawikin's second early-market screen is a government committed to macroeconomic stabilization and bringing high inflation under control. — Graham & Doddsville Interview.
- Require an investable market: His third factor is a functioning capital market with at least a few investable stocks; he says a market need not offer a large list of companies. — Graham & Doddsville Interview.
- Banks magnify a country's trajectory: Sawikin views a country's bank as a leveraged way to invest in its growth, while warning that banks can suffer especially severe losses when conditions reverse. — Graham & Doddsville Interview.
- Find each country's comparative advantage: Sawikin searches for sectors suited to each market's economy—for example, coal in Mongolia and banking or retail in the Baltics at the time of his interview. — Graham & Doddsville Interview.
- Visit before dismissing a market: Sawikin says his January 1994 visit to Russia gave him first-hand confidence in the existence of investable assets despite the country's difficult conditions. — Graham & Doddsville Interview.
- A first decline may be only the start: Sawikin cautions value investors that an emerging-market stock's initial drop can precede a wider macroeconomic collapse, so averaging down requires a fresh country-level assessment. — Graham & Doddsville Interview.
- Travel tests the thesis: Sawikin says visits to companies and stores can reveal management quality and operational problems that financial statements or broker reports miss. — Invest Like the Best Podcast.
On Portfolio Management and Strategy
- Diversify against sudden failures: Sawikin argues that frontier-market companies can fail abruptly and liquidity can vanish, so a fund should not depend excessively on a single position. — Graham & Doddsville Interview.
- Treat a ten-percent position as aggressive: For Sawikin, a holding above ten percent of an emerging-markets fund warrants particular scrutiny because it concentrates risks that may surface suddenly. — Graham & Doddsville Interview.
- Size for value, liquidity and management: Sawikin described a typical 4–6% holding when value, liquidity, management and macro conditions all looked strong, with smaller weights when any factor was weaker. — Graham & Doddsville Interview.
- Know the limits of your edge: In the Columbia interview, Sawikin said Firebird found it hard enough to maintain an edge in the twelve markets where it was then active; he was wary of stretching across all global emerging markets. — Graham & Doddsville Interview.
- Be selective buying, decisive selling: Sawikin gives qualified approval to Fred Berliner's advice to demand an attractive entry price but sell promptly once the investment decision has changed. — Yet More Investing Truisms.
- Do not let a limit order delay an exit: After deciding to sell, Sawikin warns that repeatedly lowering a limit order can leave an investor chasing a falling price. — Yet More Investing Truisms.
- Detach from former favorites: Sawikin recalls that trader Fred Berliner used unromantic labels for stocks to avoid attachment; he connects that discipline to exiting a former winner when its case has deteriorated. — Yet More Investing Truisms.
- Match liquidity to cash needs: Sawikin adopts Bob Spiegel's warning to sell before cash is urgently needed; Firebird's 2008 liquidity squeeze showed him the cost of selling assets under pressure. — Yet More Investing Truisms.
- Judge process against outcomes: Sawikin argues that a disciplined investment process does not excuse consistently mediocre results, particularly when a manager is responsible for outside capital. — Yet More Investing Truisms.
- Markets are not closed betting systems: Sawikin contrasts his friend Brom Keifetz's data-driven sports betting with investing, where changing market conditions make a repeatable process less certain. — Yet More Investing Truisms.
- Let exceptional holdings compound: Sawikin notes that a few works came to account for much of several major art collections' value, illustrating how positive skew can reward holding rare winners. — Value Investing and Art Collections.
- Hold champions with judgment: Sawikin favors keeping long-term compounders while trimming sparingly and reconsidering them if valuation or fundamentals change; he does not advocate never selling. — Value Investing and Art Collections.
- Trading around a position takes discipline: Sawikin says selling an appreciated holding with plans to rebuy it later is emotionally difficult and can fail when a bull market offers no attractive re-entry. — Value Investing and Art Collections.
- Examine your mistakes: Sawikin says he dwells on investment mistakes as part of learning from them, while recounting costly examples in the interview. — My Worst Investment Ever Interview.
On Career and Life
- A career fork: In his early thirties, Sawikin faced a choice between returning to law and committing full-time to a new Russia-focused investment partnership. — I Didn't Think I Needed Therapy.
- Use an outside observer when stuck: Sawikin sought a career counselor while struggling with that decision and discovered the counselor was a licensed psychotherapist. — I Didn't Think I Needed Therapy.
- Self-knowledge may need help: Sawikin says the counselor helped him see why independent work suited him; he offers it as a personal example of an outside observer revealing a blind spot. — I Didn't Think I Needed Therapy.
- Curate real-time information: In the interview, Sawikin recommended Twitter as a real-time source of investment ideas and news, provided a reader follows informed people and evaluates what they post. — My Worst Investment Ever Interview.
- Write beyond investing: Sawikin describes The Falling Knife as a publication about investing as well as marriage, family, culture and other interests. — The Falling Knife — About.
- Write the novel: Before committing full-time to Firebird, Sawikin published the 1995 novel The Education of Rick Green, Esq., about a lawyer. — I Didn't Think I Needed Therapy.
- Value loyal early backers: Sawikin warns that institutions arriving only after a strategy becomes fashionable may signal a crowded market, while early believers can remain supportive through downturns. — Fundraising for Young Learners.
Learn more:
- My Worst Investment Ever: Harvey Sawikin — Do Your Own Homework
- Harvey Sawikin — Investing Truisms: Are They True?
- Graham & Doddsville: Interview with Harvey Sawikin
- Harvey Sawikin — Trump Smash Dollar (?)
- Invest Like the Best, Episode 75: Emerging Market Opportunities
- Harvey Sawikin — Yet More Investing Truisms
- Harvey Sawikin — Value Investing: Lessons from Major Art Collections
- Harvey Sawikin — I Didn't Think I Needed Therapy